Author: Paul Choi
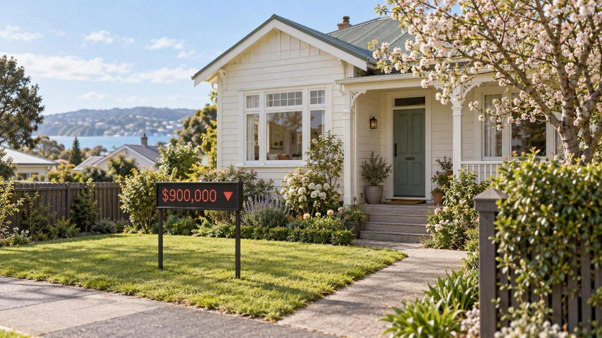
Imagine for a moment that there was an electronic sign outside your house showing its market value every day.
On Monday, it says $950,000. On Tuesday, it drops to $930,000. By Friday, you walk outside and it is sitting at $900,000. By then, most of us would be paying close attention to that sign.
Nothing obvious has happened to the house, yet somehow, we feel $50,000 poorer. The questions would probably start quickly: Why is it falling? Is it just my house? Should I be worried? Before long, the question would become: Should I be doing something?
That might sound a little unrealistic, but property prices can surprise us when they are tested. Anyone who has watched a property go under the hammer knows that the number we had in our head, the valuation, and what someone is prepared to pay can be quite different things. After all, the final price is influenced not only by what one person is willing to pay, but also by how many others are prepared to compete for it.
Thankfully, we do not get to watch that process play out with our own house every day. There is no price ticker outside constantly reminding us of what someone might be prepared to pay for it.
We might get a valuation occasionally, look at an online estimate or, as we do, take a little too much interest in what the house down the road sold for. But even the house down the road is not necessarily comparable to ours. It might look similar and have the same number of bedrooms, but every property is different. Its position, condition, layout, renovations, and plenty of other factors can influence what someone is prepared to pay.
In reality, we do not know exactly what a house will sell for until it is tested in the market.
Financial markets are quite different. If I own a share in a listed company, shares in that company are regularly bought and sold, allowing us to see the market price moving in real time.
That transparency is incredibly useful, but I sometimes wonder whether it plays a few tricks on us as well. Does something feel more risky simply because we can see its price moving?
After all, seeing a price move and understanding the risk we are taking are not necessarily the same thing. Property values move too. We just do not experience those movements in quite the same way.
Familiarity has something to do with it as well. If we have owned property for a long time, we tend to understand it. We know things break, tenants sometimes leave and there will inevitably be another bill that arrives at exactly the wrong time. After a while, those risks become familiar and I wonder if that familiarity starts to feel a little like safety.
I have experienced that myself with a property in Wellington. For a long time, I had never really struggled to find tenants and, if I am honest, I probably just assumed that would continue. Then COVID came along and the property sat vacant for around five months.
I certainly did not see that coming.
Fortunately, I had enough of a financial buffer that I could continue meeting the property’s cost without being forced into a decision simply because something unexpected happened.
Looking back, knowing property reasonably well had not removed the risks. It had simply made me more comfortable with the risks I knew about, sometimes to the point where I almost stopped noticing them. What caught me out was something I had never really considered.
Imagine someone told you tomorrow that your home had fallen 10% in value. What would you actually do?
Probably not much. You might not be thrilled about it, but unless you needed to sell, it might not change a single decision you make.
Yet when we can see the value of an investment portfolio moving in real time, it can be much harder to do nothing. We start wondering whether we should sell, wait until things settle down or move the money somewhere that feels safer.
At the same time, market falls tend to attract plenty of headlines, adding another layer of noise while we are already watching the value closely. Before long, it can feel as though there are reasons everywhere telling us we should be doing something.
We normally assume that more information helps us make better decisions and most of the time it probably does. But more information does not automatically mean a better decision. Constantly knowing the price of something, combined with all the noise around it, can create pressure to act when perhaps the more important thing is to understand whether anything fundamental has actually changed.
Maybe the better question is not whether something feels safe, but why it feels safe. Is it because we genuinely understand the risks and have thought about what might happen? Or is it
partly because it is familiar, its price is not flashing in front of us every day, and nothing has happened recently to make us question it?
This is something I think about often when it comes to financial planning. We naturally look for certainty, particularly with money we have worked hard to build, but I am not sure certainty is available to us.
What we can build is confidence.
For me, confidence comes from understanding what we own and why we own it, recognising the risks involved, and accepting that things will not always unfold as expected.
Good financial planning is not about removing that uncertainty. It is about being better prepared to make sound decisions when uncertainty arises.